Homeowners insurance pays to repair or rebuild your house, replace your belongings, and cover your legal liability — but only for the perils the policy names and only up to the limits it declares. Most surprises come from the gaps: flood, sewer backup, mold, gradual wear, and jewelry.
If you are trying to sort out what homeowners insurance covers before a loss rather than after, the fastest route is the declarations page at the front of your own policy. Everything else in this guide is a way of reading that page correctly.
Table of Contents
- What Homeowners Insurance Covers and What It Does Not: A Guide
- What Does Homeowners Insurance Typically Cover?
- How Does Coverage for the Home and Personal Belongings Work?
- What Homeowners Insurance Usually Does Not Cover
- Which Losses May Need Separate Policies or Add-Ons
- How Deductibles, Limits, and Exclusions Affect Your Protection
- What Not to Say to Your Insurer Before or During a Claim
- How to Check Your Coverage Before You Need It
- Frequently Asked Questions
- What does homeowners insurance cover typically?
- What are three things that are not covered by homeowners insurance?
- Is hazard insurance the same as homeowners insurance?
- Does homeowners insurance cover a burst pipe and the resulting mold?
- What is the most common damage to a home that insurance does not cover?
- What happens if my homeowners insurance denies a claim?
- Conclusion
What Homeowners Insurance Covers and What It Does Not: A Guide
A homeowners policy is a contract that pays for sudden, accidental damage to a residence and for the liability that comes with owning it. It is not a promise that every problem with the house gets fixed. Anything the form excludes stays excluded until you buy an endorsement or a separate policy.
If your mortgage statement lists hazard insurance, that is almost certainly the same contract under a lender’s older name for it. Hazard insurance and homeowners insurance are not two separate policies on one house — the lender just uses the term because it predates how the coverage is usually described now.
The same confusion shows up around home warranties, which pay for repair or replacement of mechanical systems and listed appliances that break from age. Insurance responds to a covered peril. A warranty responds to a worn-out part. A service contract sold by a plumber is neither, and neither one substitutes for flood or earthquake coverage.
Forms are written by the state you live in, and carriers add their own endorsements on top, so two policies with identical labels can carry different exclusions. Treat the specifics in your own declarations page as authoritative and treat any general explanation, including this one, as a starting point.
What Does Homeowners Insurance Typically Cover?
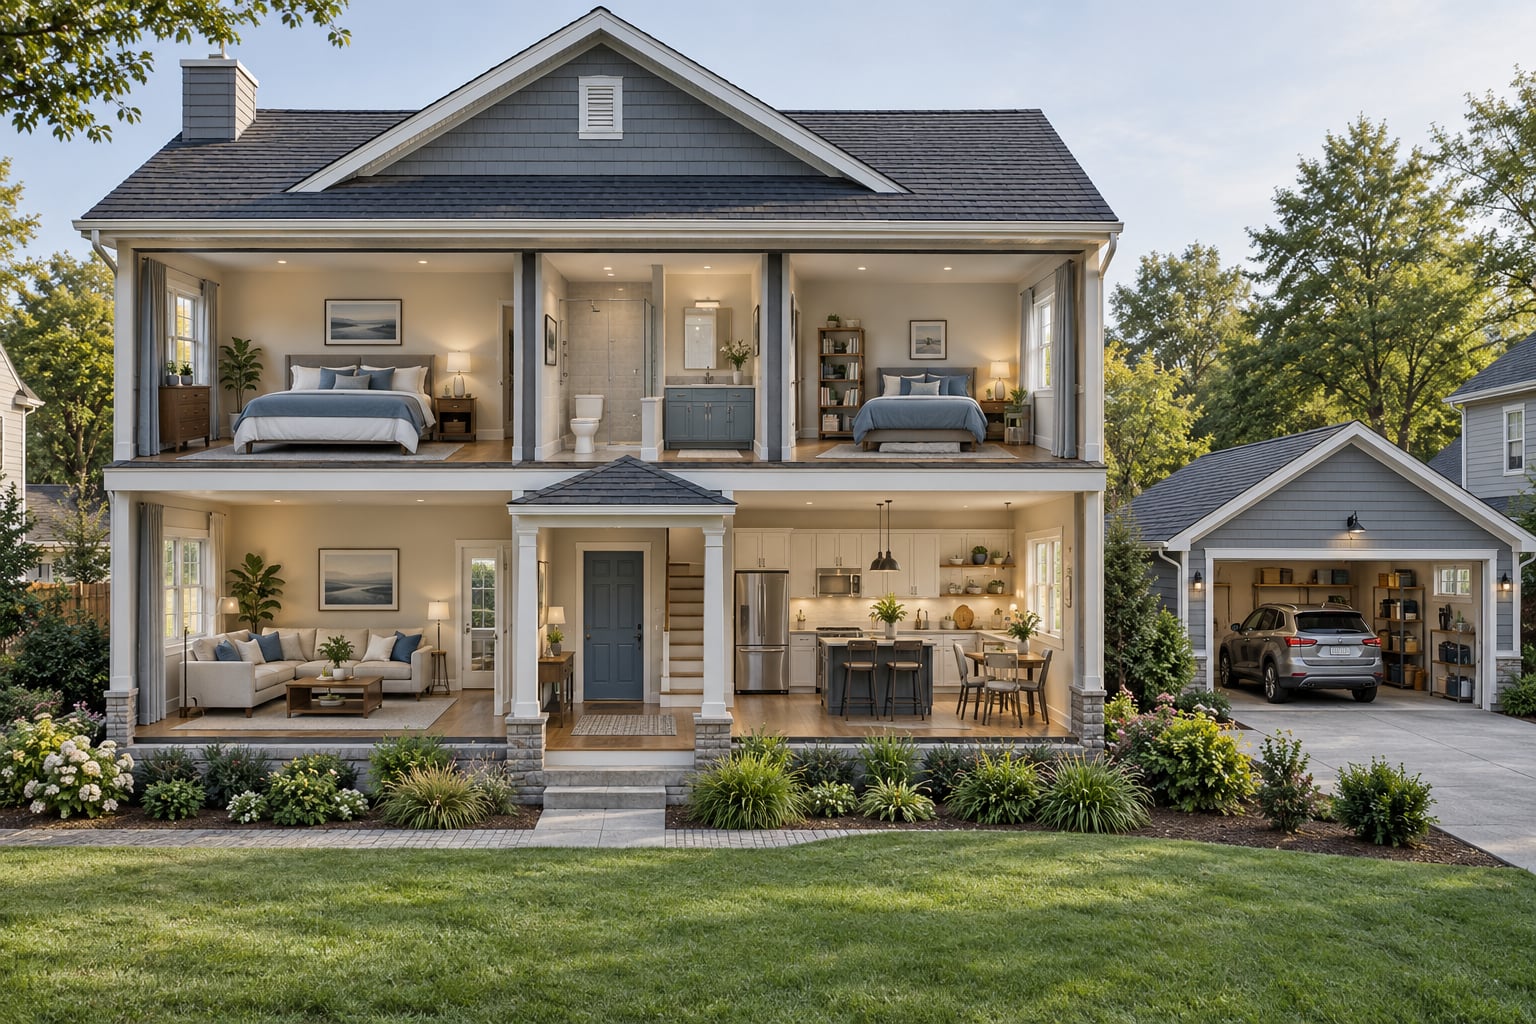
Most owner policies carry six numbered coverage parts, and each one answers a different question about the loss.
- Coverage A, dwelling: rebuilds the house itself, including the roof, siding, foundation, built-in cabinets and attached garage.
- Coverage B, other structures: covers detached structures such as a shed, detached garage or fence, usually capped at a share of the Coverage A limit.
- Coverage C, personal property: pays for your furniture, clothing, electronics and stored belongings both inside and, in some policies, in a storage unit.
- Coverage D, loss of use: pays additional living expenses if the home becomes unlivable, including a deductible or documented rent increase.
- Coverage E, personal liability: covers claims from guests injured in your home, or damage you cause to a neighbor’s property.
- Coverage F, medical payments: pays injury-related medical bills for anyone hurt at your property regardless of fault, with no deductible.
The named perils you will see in these sections include fire and smoke, lightning, windstorm and hail, the weight of ice, snow and sleet, theft, vandalism, malicious mischief, falling aircraft or objects, smoke from a fire, explosion, riot or civil commotion, volcanic eruption, and damage caused by vehicles or aircraft.
An HO-3, the form most owners carry, is an open-perils policy: it responds to any sudden, accidental peril unless that peril is specifically excluded. HO-1 and HO-2 forms are named-peril policies, which respond only to the listed events, and older homes on those forms often settle at actual cash value instead of replacement cost.
| Situation | Usually covered | What to check |
|---|---|---|
| Fire and smoke damage | Yes | Damage from a covered peril, not a neglected chimney |
| Hail or falling tree on the roof | Yes | Age of roofing material, since some carriers limit older roofs |
| Burst pipe water damage | Yes, generally | The resulting damage is covered; the pipe itself usually is not |
| Theft or vandalism | Yes | Proof of ownership and purchase, such as a receipt or a photo |
| Slip-and-fall injury to a guest | Yes, under Coverage E | Your liability limit and whether it covers events on your property |
| Flood from rising surface water | No | Separate flood policy through the NFIP or a private carrier |
| Earthquake or sinkhole | No | Separate earthquake policy, priced by location and construction |
| Sewer or sump pump backup | No | Water backup endorsement, which is priced separately |
| Mold from a covered water loss | Sometimes | Limits on remediation are low and separate from the main limit |
| A 20-year-old roof failing on its own | No | Wear and tear and deterioration are excluded outright |
| A $4,000 diamond ring stolen | Only above the sublimit | Scheduled personal property endorsement for valuables |
How Does Coverage for the Home and Personal Belongings Work?
Dwelling and personal property settle in two different ways. Replacement cost means the insurer pays for a new item or rebuild at today’s prices, minus your deductible and minus any depreciation they document. Actual cash value subtracts depreciation first, so a ten-year-old sofa pays out based on what it would have sold for.
Personal property also carries sublimits. Cash, jewelry, furs, antiques, silverware, golf equipment and boats each have a per-item and per-category cap in a standard policy. A laptop is usually covered at full value inside Coverage C; a diamond necklace is not.
Documentation matters more than most people expect. A home inventory with photographs, model numbers and receipts speeds up both the claim and any replacement-cost argument. Without proof of what you owned and what it cost, the conversation turns into recollection, and recollection loses.
What Homeowners Insurance Usually Does Not Cover
Flood is the first exclusion nearly every carrier applies, and it means water rising from the ground, from a river, or from a body of surface water. Water that comes from inside the house is a different situation entirely, which is why a burst pipe and a flooded basement produce very different outcomes.
Other common exclusions, using the language your declarations page will contain:
- Flood, tidal water and water rising from the ground
- Earthquake, landslide, mudflow and, in most states, sinkhole
- Sewer, drain and sump pump backup, plus water that backs up through a hose
- Wear and tear, deterioration, rot, rust, fungus and mold that grows on its own
- Pest infestation, termites and vermin damage
- Failure of a component or system that broke down rather than got damaged
- Power failure or outage, including damage from a surge when the utility did not cause it
- Intentional damage or neglect caused by someone living in the home
- Damage from government action, war, nuclear hazard or radioactive contamination
- Loss of data, cash and documents such as deeds and titles
- Beauty damage and purely cosmetic changes, and normal settling or cracking
- Trees, plants and lawns, except sometimes after a covered peril under a specific endorsement
Homeowners on older houses should read the mold and water-damage exclusions closely. Owners of pre-1973 construction frequently see language that responds differently to moisture conditions the structure cannot handle, which is a large part of why HO-8, the older-home form, exists.
Which Losses May Need Separate Policies or Add-Ons
Flood requires its own policy. The National Flood Insurance Program is the federal route, and private flood carriers also write coverage with different limits and pricing. If you live in a mapped high-risk zone and have a mortgage, the lender will usually require it.
Earthquake coverage is written separately and priced by distance from a seismic zone, building type and frame construction. It is cheap in some states and expensive in others, and the premium often makes more sense once you compare it against the deductible you would otherwise carry.
An umbrella policy extends personal liability above the limit on your homeowners policy, which matters most if you have a pool, a rental unit, a dog with a bite history, or a trampoline. Scheduled personal property endorsement adds a stated value for jewelry, art, instruments and collectibles. Water backup covers sewer and sump overflows. Ordinance or law coverage pays for code upgrades a rebuild would otherwise leave you paying for. Equipment breakdown covers an appliance or a mechanical system failing on its own. Service line protection responds to a broken supply line between the house and the utility connection.
Identity theft coverage and loss-of-use extensions are smaller additions that some carriers fold in at low cost. Ask which ones your carrier includes free before paying a separate premium for the same thing.
How Deductibles, Limits, and Exclusions Affect Your Protection
Claims settle in a fixed order. The loss must first trace to a covered peril rather than an exclusion. Then the insurer applies the deductible, then it measures the loss against the relevant limit, then it applies the valuation method the policy promises. A claim can fail at any one of those four steps even when it feels like it should be covered.
Consider a kitchen where a frozen pipe failed over a long weekend. If the water damaged the floor cabinets, drywall, counters and about 12,000 in belongings, and you carry a 1,000 all-perils deductible with a 100,000 Coverage C limit, the payout under replacement cost coverage lands near 100,000 minus the deductible if the damage reached the limit, not 100,000 plus the deductible. Under an actual cash value settlement, the same loss drops by depreciation on each item, and a ten-year-old dishwasher pays out at a fraction of its sticker price.
Two trends make those numbers harder to ignore. More policies now carry deductibles set as a percentage of the dwelling limit rather than a flat dollar figure, so a higher-priced house absorbs a much larger first check before coverage begins. And carriers can decline to renew or narrow coverage at renewal in many states, which is why owners who shop their market annually tend to be less surprised at renewal time.
When a claim is denied, the most common reasons are a peril that turns out to be excluded, a limit exceeded, missed policy conditions such as failing to report the loss promptly, and a valuation dispute. Read the denial letter for the specific exclusion or limit cited, request the full policy including all endorsements in force on the date of loss, and put the appeal in writing to the carrier’s complaint department. If that fails, most states have a department of insurance you can file with, and regulators generally require a carrier to complete an internal review first.
What Not to Say to Your Insurer Before or During a Claim
The live question on this topic is what to avoid saying, so here is a short version. Do not speculate about the cause, do not admit responsibility or assign blame, and do not describe the damage as pre-existing before you have actually inspected it. Do not promise a guest or a contractor that insurance will pay for something. Do not discard damaged items before the adjuster sees them, and do not say “I guess it happened that way” when you do not know.
Say instead what you observed and when, photograph everything before cleanup, keep damaged materials, and keep a written log with receipts. Anything you say to an adjuster may end up in a recorded statement, and a recorded statement is difficult to walk back.
How to Check Your Coverage Before You Need It
Put the declarations page next to a current inventory of what you own and work through it once a year. The declarations page is a single sheet or two that states your name, the address insured, the carrier and policy number, the policy period, the form number, and each coverage limit and deductible in plain numbers. Everything else in the policy is commentary on that page.
Check six things. First, is the Coverage A limit high enough to rebuild the house, not just to pay off the mortgage. Second, do your belongings total more than Coverage C allows. Third, do you know your liability limit and whether your umbrella extends it. Fourth, read the exclusion list and mark every one that fits your property, especially water backup, mold, flood and any roof age language. Fifth, list the endorsements attached to the policy and confirm you know what each one covers. Sixth, save the agent’s direct number somewhere outside your email, because the first call after a loss should go to a person, not a claims queue.
Then do the unglamorous part: photograph every room, walk the attic and the basement, and record what is actually there. Property you cannot describe cannot be replaced. Homeowners who inventory their belongings consistently report faster claim handling and far less argument at settlement, and it costs a weekend.
Finally, ask your agent the two questions most people skip: which covered peril worries you most for this specific house, and what would this policy not pay for here. A licensed agent can answer both in ten minutes, and if they cannot, that tells you something useful about the carrier.
Frequently Asked Questions
What does homeowners insurance cover typically?
A standard owner policy, usually the HO-3 open-perils form, has six parts: dwelling (A), other structures (B), personal property (C), loss of use (D), personal liability (E) and medical payments (F). Dwelling rebuilds the house after a covered peril, personal property replaces belongings, loss of use pays extra living expenses, and liability covers injury to guests or damage you cause. Flood, earthquake, sewer backup and wear and tear are excluded.
What are three things that are not covered by homeowners insurance?
The three most commonly discovered exclusions are flood from rising surface water, sewer or sump pump backup, and damage from wear and tear or gradual deterioration. A fourth close behind is mold that develops on its own rather than as part of a covered water loss. Earthquake, power failure, pest infestation and intentional damage are excluded as well. Each of these has a separate endorsement or policy available for most owners.
Is hazard insurance the same as homeowners insurance?
In most cases, yes. Hazard insurance is the older term lenders and servicers use for the same owner policy, particularly for the hazard coverage that protects the structure against fire and wind. What it is not is an all-perils policy: flood, earthquake, sinkhole and sewer backup sit outside it. If your mortgage escrow shows a hazard insurance line, that is generally your homeowners premium collected and paid through the servicer.
Does homeowners insurance cover a burst pipe and the resulting mold?
The water damage from a sudden, accidental burst pipe is generally covered because the pipe failed without anyone failing to maintain it. The cost of repairing or replacing the pipe itself usually is not, since that counts as maintenance. Mold is the harder question: remediation caused by a covered water loss may be paid within a separate and fairly low limit, while mold that results from long-term moisture, condensation or a slow leak is excluded entirely.
What is the most common damage to a home that insurance does not cover?
Gradual water intrusion is the most common uncovered loss, including moisture that seeps in slowly through a foundation wall, a window frame or a failed roof flashing and causes rot or mold over time. Flood from rising surface water and sewer backup run close behind, and insurance carriers handle those through separate flood policies and water backup endorsements.
What happens if my homeowners insurance denies a claim?
Read the denial letter and find the exact exclusion, limit or policy condition the carrier cited, then request the complete policy with every endorsement that was in force on the date of loss. Submit a written appeal to the carrier’s complaint department with photographs, receipts and an inventory. Most states require an internal review first, and after that a complaint to your state department of insurance, which handles appeals for free.
Conclusion
Start with one task: put your declarations page next to a current list and photographs of what you own, and mark every limit or exclusion that leaves money on the table. Then take that marked page to a licensed agent and ask what would not be paid for in a fire, a burst pipe and a flood at your specific house.